Storm Damage Roofing Company vs. General Contractor in Colorado Springs
The difference comes down to who decides the scope of work. On a remodel, the homeowner and the contractor agree on it before anyone signs. On hail damage, an insurance adjuster decides it, and the contractor who cannot read that process is guessing at the number.
We are The Rich Co Inc, and homeowners looking for the best roofing company in Colorado Springs, CO often come to us because we keep licensed insurance adjusters on staff. Our team carries more than forty years of combined experience across El Paso County. Our crew and our claims people work under one roof, so the team tarping a leak is the team reading the policy language. A general contractor without adjuster experience and a roofer without construction depth each solve half of the same problem.
Where a General Contractor Genuinely Fits
A general contractor earns their reputation on work with a fixed scope. A kitchen, an addition, a fence, a deck. Everyone agrees what the job is, what it costs, and when it finishes, and the contractor manages trades against that agreement.
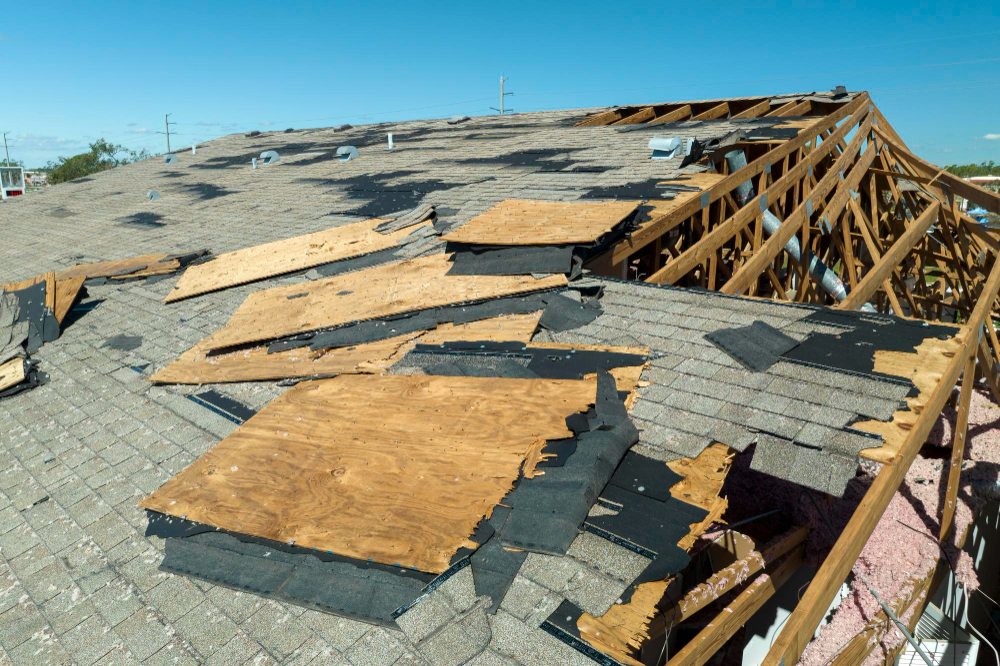
Hail does not behave that way. Nobody in the conversation sets the scope, because the carrier’s adjuster inspects the roof and writes the estimate the carrier will pay against. A skilled general contractor can still frame and execute the repair correctly, but cannot predict what the adjuster will approve. A guess that undercounts the damage turns into a bill the homeowner covers later, and that gap has nothing to do with construction skill.
How a Storm Specialist Changes the Claim Outcome
A storm damage roofing company builds its process around the claim rather than the shingles. Ours runs through reviewing the damage, documenting it formally, filing with the carrier, and negotiating the settlement. The people inspecting the roof are the same people arguing the scope weeks later.
That continuity shows up most clearly when a carrier pushes back. An insurer that undervalues a claim gets a response from licensed adjusters. The alternative is a homeowner reading policy language for the first time.
We also gather and organize the incident reports, records, and photographs from the beginning, which is precisely what a disputed claim needs to succeed. A contractor without claims staff has nothing equivalent to offer once the answer comes back as no.
Carrier comes back with a number that will not cover half the Colorado Springs roof? Give us a call at (719) 287-5385, and our adjusters will take the supplement and the documentation from there.
Spotting a Contractor Who Should Not Be Near Your Claim
Storms bring in outfits that are not local and will not be here if the repair fails or the claim gets challenged. A truck with an out of state plate outside a neighbor’s house is not a recommendation. Signing on the spot skips every check that protects the homeowner afterward.
The same caution applies to a general contractor working outside their usual scope. A construction license does not include adjuster training. Our piece on spotting storm chasers and roofing scams covers the pressure tactics that follow a hailstorm. The warning signs are consistent enough to list.
- Pressure to sign a contract the same day the estimate is handed over
- An out of state plate parked on the block right after a storm
- A crew skipping permits on work that normally requires them
- A demand for a large payment before anything starts
- No local address, and a phone number that stops answering after the sale
Spotting roofing scams after storms is far easier once you have a local roofer on your side, so call us for an honest inspection before you sign anything.
What Each Type of Company Does When the Carrier Says No
This is the practical fork in the road. A general contractor at that point can rebid the job, suggest an appeal, or tell the homeowner to call the insurer. None of those move the file.
A company with adjusters on staff files a supplement with new documentation attached and negotiates the disputed amount directly. We keep the homeowner updated on claim status throughout, so nobody is calling the carrier for news we already have. Whether to bring a contractor in before filing is a fair question on its own. Our post on calling a contractor before filing a claim works through the timing.
The order matters more than most homeowners expect. An estimate that reaches the carrier first becomes the baseline everything afterward gets measured against, and moving a baseline takes evidence rather than argument. A homeowner who has an independent inspection in hand before that point is not asking the insurer to reconsider a number.
They are handing over documentation the carrier has to answer, which is exactly why pairing roof claims and right contractor decisions early puts you in the stronger position. Call us before the first estimate goes in, and we will build that file with you. Documentation that was gathered the same way the industry gathers it, which is a very different conversation to start.
Commercial Property Changes the Calculation Again
A commercial building raises the stakes on both counts. The roof area is larger, the documentation standards are tighter, and tenants in Colorado Springs, CO notice every day the work runs long. An owner also tends to want the scope in writing before anything starts.
A general contractor may handle the build out beautifully and still be the wrong choice for the storm claim attached to it. Our commercial roof repair work goes through the same independent inspection and formal documentation a house does. A property manager answering to an owner needs the paper trail as much as the repair.
Frequently Asked Questions
Yes. We offer free roof inspections seven days a week, with no cost and no obligation. You’ll find out whether hail did real damage before you decide anything about a claim.
Before is usually better. The first estimate the carrier receives becomes the baseline that everything afterward is measured against. If you have an independent inspection and documented damage in hand before you file, you start the claim with evidence instead of trying to argue a number up later.
Our licensed adjusters prepare a supplement with new documentation attached. We collect the photographs, records and incident reports from day one, which is what a disputed claim needs. You also get regular updates on your claim’s status, so you won’t be left calling the carrier for news.
Yes. Commercial roofs go through the same independent inspection and formal documentation as residential roofs. That gives property managers and owners the paper trail they need alongside the repair.
The estimate that reaches your carrier first shapes what gets paid, so it pays to have adjuster experience on your side from the start. The Rich Co Inc brings more than forty years of combined experience across El Paso County, with licensed adjusters and roofing crews working as one team. Call (719) 287-5385, free inspections seven days a week, with no cost and no obligation.
Related Topics: